
The deposit path
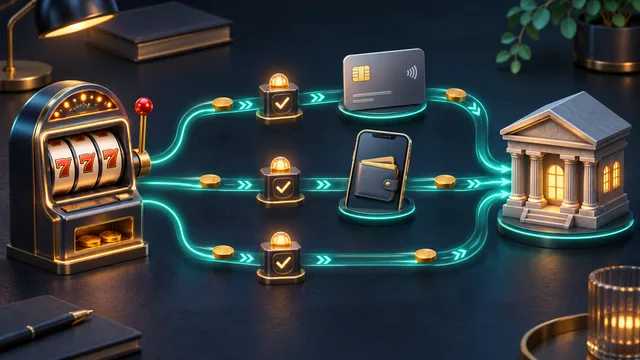
The operator submits a card transaction using the details or token provided by the customer. The bank may approve it, decline it or apply a gambling block. Strong customer authentication can add an app or one-time-code step. Use only a card held in the gambling account holder’s name.
Licensed gambling businesses in Great Britain must not accept credit-card payments, including credit funding disguised through a money service business. A card accepted by a form is not evidence that it is lawful or appropriate; the operator must identify and prevent credit-card gambling.
The withdrawal path
Card withdrawals may use a payout capability that is different from the purchase transaction used for a deposit. The issuer or card may not accept that payout type. An expired or replaced card can also interrupt the route.
Before depositing, ask:
- Is this debit card eligible for withdrawals at this operator?
- How will a balance be returned if it is not?
- Does the operator use the original card before another method?
- What name and ownership evidence may be required?
- Does the quoted time cover operator review, card processing or both?
If a card payout fails, obtain the attempt time and error category. A verified bank transfer may be the alternative, but the operator should explain the change.
Bank gambling blocks
Many banks offer voluntary gambling-payment controls. A block can stop new deposits, but it should not be treated as a reason to seek a workaround. Incoming credits and purchase authorisations are different transaction types, so contact the bank only after the operator identifies what it attempted.
If a block reflects a decision to stop gambling, keep it in place and consider self-exclusion and support rather than switching methods.
Verification and safe evidence
The operator may need to verify card ownership. Follow its masking instructions. Do not disclose the PIN, CVV, full online-banking credentials or one-time security codes. Upload evidence only through the official secure channel.
The UKGC requires age and identity checks before gambling and says information reasonably available earlier should not be deferred until withdrawal. A later legal or risk-based check may still be valid; ask what requirement is open.
Limits, fees and timing
Separate these fields:
| Field | What it means |
|---|---|
| Deposit minimum/maximum | Amount the cashier permits in one period or transaction |
| Withdrawal minimum/maximum | Amount accepted for a payout request |
| Operator review | Time before the payment instruction is released |
| Network arrival | Time after release to the card issuer |
| Fee | Operator, bank, provider or currency cost |
Do not label a card “instant” without defining which stage is instant. Save the current cashier terms and compare them with the withdrawal timeline.
When a debit-card withdrawal is missing
Confirm whether the request is still pending, approved, sent, rejected or returned. If sent, ask for a trace or transaction reference and the release date. Give that information to the bank. If not sent, the operator—not the bank—is the party that can explain the internal review.
For a comparison with a wallet route, see debit card vs PayPal.
Sources
- UK Gambling Commission, gambling using a credit card, checked 16 November 2026.
- UK Gambling Commission, payment methods and services—LCCP 5.1.2, checked 16 November 2026.
- UK Gambling Commission, age and ID verification, checked 16 November 2026.