
What happens on deposit
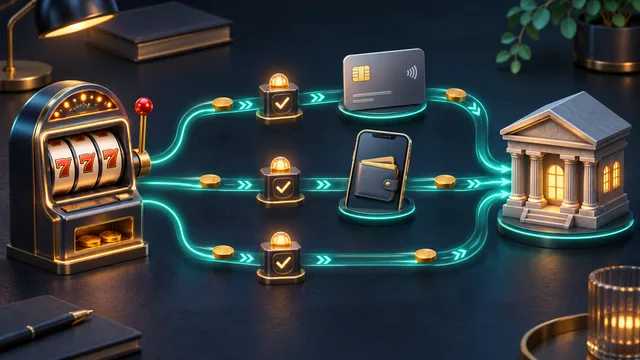
The customer chooses a bank, signs in or authenticates through the bank’s controlled journey, reviews the payee and amount, and approves the payment. The gambling operator should not receive the customer’s online-banking password.
Stop if the payee, amount or return address differs from the expected journey. Never disclose full banking credentials to casino support or a person claiming to be a payment agent.
How withdrawals may work
The return can be a separate bank payout to a verified account rather than a reversal of the original payment. Ask whether the operator calls it open banking, bank transfer or another name in the withdrawal screen. Confirm the masked account and expected reference.
A successful open-banking deposit establishes neither a universal withdrawal time nor automatic approval. The operator may still perform account and transaction checks before release.
Ownership and verification
Use an account held by the gambling account owner. If a joint account is accepted, check what evidence is required. The operator may ask for a statement or bank-account proof showing the name and relevant details.
Upload only through the official secure channel. Do not provide passwords, PINs, complete security answers or one-time authorisation codes. Age and identity verification should occur before gambling; a new legal obligation may still justify a later request.
Common failure points
| Point | Possible issue | Next check |
|---|---|---|
| Bank selection | Bank not supported for that flow | Use the operator’s current list, not an old article |
| Authentication | Session expires or approval is cancelled | Restart only through the official cashier |
| Payment instruction | Payee or amount is rejected | Ask for the transaction reference and status |
| Operator allocation | Payment sent but not credited | Match bank reference, time and exact amount |
| Withdrawal | Verified payout account differs | Confirm destination before resubmitting |
Do not send a second deposit merely to fix an unallocated first one. Ask the operator to trace the original reference.
A failed return to the casino page is not the same as a failed bank payment. After approving a transaction in your bank app, inspect the bank history and casino ledger before trying again. Record whether the bank shows no transaction, a pending entry or a completed transfer. The casino's loading screen alone cannot tell you which of those states exists.
If the bank shows a transfer but the casino has not credited it, gather the payment reference, amount, currency and time. Ask the operator to check for an unmatched incoming payment. Do not replace the original reference with a description invented for a second attempt; the provider may need the exact reference generated by the payment flow. Keep any confirmation page or receipt that identifies the payment initiation provider.
If approval never completed, note where the process stopped: bank selection, authentication, consent or the return to the merchant. That detail helps support distinguish a bank connection problem from an account restriction. Avoid sharing a screen recording that exposes a banking passcode or authentication prompt. A written description of the stage and a redacted error message is usually a safer starting point for diagnosis.
Check any bank block or personal gambling control before pursuing another route. A declined payment can reflect a deliberate restriction rather than a technical fault, and it should not be bypassed by switching accounts. Where the problem is genuinely technical, ask whether the original payment instruction remains active before restarting. After a retry is approved, review both histories for duplicate entries and keep the references separate. The issue is closed only when the casino credit and bank movement reconcile, or the unused instruction is confirmed as cancelled.
Keep the recipient reference supplied by the bank flow unchanged when asking for a trace. A shortened copy can omit a character needed to match the incoming payment. If you redact account details for privacy, leave the transaction reference intact unless the provider specifically asks for a different safe format.
Bank blocks and personal controls
A bank may offer a gambling block or other spending control. Open banking should not be used to evade that decision. If the block reflects concern about gambling, keep it active and use responsible gambling support rather than searching for a different rail.
Timing, limits and charges
The bank authorisation may be quick, but withdrawal includes operator review and a separate receiving stage. Record deposit and withdrawal limits independently. Check for operator, payment-provider and currency charges; “bank payment” does not prove there is no cost.
For a traditional account-to-account comparison, see bank transfers. For all payment families, use the deposit method checklist.
Sources
- UK Gambling Commission, payment methods and services—LCCP 5.1.2, checked 16 November 2026.
- UK Gambling Commission, age and ID verification, checked 16 November 2026.
- UK Gambling Commission, withdrawal expectations, checked 16 November 2026.