
What open banking means in a cashier
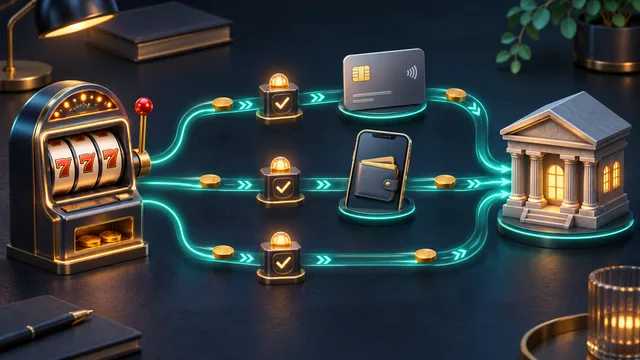
Open banking is the regulated framework that lets a third-party provider initiate a payment from your bank account, or read limited account information, with your explicit consent. In a casino cashier it usually appears as a pay-by-bank option: you choose your bank, authenticate with the bank, and approve a payment the provider has prepared.
There are two distinct permissions in the framework, and they are not the same thing. Payment initiation instructs a payment. Account information access reads data such as balances or transactions. A deposit needs the first; the second is sometimes requested for verification purposes and should be explained when it is.
The providers in the chain are regulated firms. In the United Kingdom, payment and account-information providers are authorised and supervised by the Financial Conduct Authority, which is why this route exists at all rather than casinos asking for banking logins directly.
What you consent to, and for how long
Consent in this framework is specific. For a single deposit, the consent covers one payment of a stated amount to a stated payee. For account information, it covers a defined set of data for a defined period, and it can be withdrawn.
Read the consent screen rather than clicking through it. It names the provider, the permission being granted and the duration. A one-off payment consent that is presented as an ongoing data permission is a difference worth noticing, because the second one keeps working after the deposit is finished.
Consents can be reviewed and revoked in your bank’s own app, usually under a section listing connected third parties. That is the correct place to end an access permission you no longer want, and it works regardless of what the casino’s own settings offer.
| Permission | What it allows | How long it lasts | Where to revoke |
|---|---|---|---|
| Payment initiation (single) | One payment of a stated amount | That payment only | Not applicable |
| Payment initiation (recurring) | Repeat payments within set rules | Until cancelled | Bank app and provider |
| Account information | Reading balances or transactions | A defined period | Bank app, connected third parties |
| Confirmation of payee | Checking account name match | That payment only | Not applicable |
What the operator receives and what it does not
The operator receives confirmation that a payment was initiated and, when it settles, the money with a reference. It does not receive your banking credentials, and it should not receive your full transaction history unless you have granted an account-information permission that says so.
Where account information is used for verification, ask what specific checks are being run and for how long the permission lasts. A name and account-ownership check is a narrow purpose; continuous visibility of your spending is not the same thing, and the difference should be visible on the consent screen.
Data protection rules apply to whatever is collected. If you believe account data has been used beyond the consent you gave, the operator’s own data-protection contact is the first route, and the Information Commissioner’s Office is the supervisory authority for data complaints in the UK.
How it differs from a card payment
A card payment pulls funds through the card networks and carries the networks’ dispute mechanisms. An open banking payment pushes funds from your account, which makes it fast and final. There is no card-style chargeback, and the resolution route for an error runs through the provider, the bank and the operator’s complaints process.
Finality is the trade-off for low cost and speed. It is also why the confirmation screen matters so much: the moment of approval is the moment the protection shifts from a reversible authorisation to a completed transfer.
The second difference is traceability. Card payments are identified by transaction records; open banking payments are identified by the bank reference. Keeping that reference intact is the practical equivalent of keeping a receipt.
- Push payment rather than a pull: fast and effectively final.
- No card-network chargeback; errors run through bank and provider procedures.
- Identified by the bank reference, so keep the reference exactly as generated.
- Credentials never pass to the operator.
- Consent is specific and revocable where it is an ongoing data permission.
Withdrawals and method matching
Payouts on this route are normally bank transfers into the account the deposit came from, which satisfies the payment-method matching clause in most casino terms. The transfer is a separate rail from the deposit journey and may take longer.
The receiving account should be in the account holder’s name. Where it is not, expect refusal and a verification review rather than a payment, because a third-party payout raises exactly the checks a licensed operator is obliged to run.
Elapsed time is dominated by the operator’s review rather than the rail. Record the request timestamp and each status change; that record is what distinguishes a slow rail from a hold nobody has explained.
Bank blocks and personal controls
Many banks offer gambling blocks that prevent gambling payments from the account or card. Open banking is not a way around such a block, and a block should not be treated as a technical obstacle to be routed around.
If the block reflects a decision about gambling spending, keep it. The help routes linked from this site are independent of any operator, do not require a dispute and do not require closing an account first.
Where the block is genuinely unintended, the bank is the place to change it, not the casino. Operator support cannot override a bank-level control and should not be asked to try.
Timing, limits and charges
Bank authorisation can be near-instant, but a withdrawal still includes operator review and a separate receiving stage. Record deposit and withdrawal limits independently, because they are set by different parties and the lower of the two always applies.
Check for operator charges, provider charges and currency conversion separately. A bank-based route is often free on deposit and can still carry a cost on payout, and the phrase bank payment does not by itself prove there is no charge.
- Read the consent screen and note which permission is being granted.
- Confirm payee, amount and reference inside the bank’s own journey.
- Keep the reference exactly as generated.
- Check both deposit and withdrawal limits, and both sets of charges.
- Review connected third parties in your bank app and revoke what you no longer need.
FAQ
Is open banking safe for casino deposits?
The mechanism is regulated and keeps your credentials with your bank. The risks that remain are finality — there is no card-style chargeback — and granting a wider data permission than the deposit needs.
Who regulates the provider?
In the UK, payment initiation and account information providers are authorised and supervised by the Financial Conduct Authority.
Can the casino see my other transactions?
Only if you grant an account-information permission that allows it. A payment-initiation consent does not include transaction history.
How do I cancel the connection?
Through your bank’s connected third parties list. That is the authoritative place and it works independently of the operator.
Why is my withdrawal slower than my deposit was?
Because the payout includes the operator’s review before the transfer is released. The rail is only the final leg.
Open banking consent is narrower than it looks on a cashier screen. A single payment permission ends with the payment; an account-information permission can continue for months and keeps reading data after the deposit is complete. Reading which of the two you are granting takes a few seconds and determines what happens after you stop using the site.
If you want to end an ongoing permission, the reliable place is your bank’s own list of connected third parties rather than the casino’s settings. That revocation works even if the operator’s interface offers nothing, and it leaves a record in the bank app that you can point to later.
Next pages
Sources
- Financial Conduct Authority: information for consumers, checked 18 November 2026.
- Information Commissioner’s Office: your data rights, checked 18 November 2026.
- UK Gambling Commission: Licence Conditions and Codes of Practice, checked 18 November 2026.