
What the journey actually is
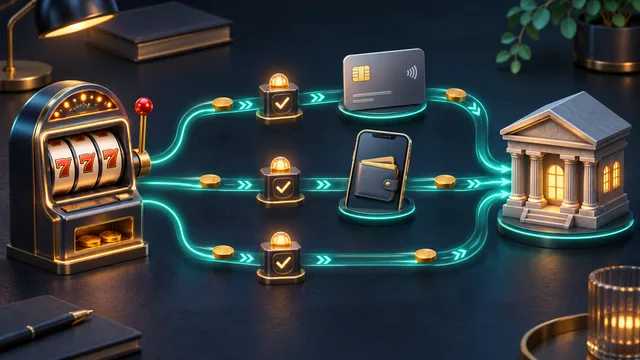
In a bank-initiated payment you do not hand card details to the casino. You select your bank in the cashier, you are taken into your own bank’s authentication, you review the payee and the amount inside the bank’s own interface, and you approve the payment there. Control of the authorisation sits with the bank, not with the gambling site.
That design is the main security advantage. The operator never receives your online-banking credentials, and it should never ask for them. Any request for a banking password, a full card number or a one-time code outside the bank’s own journey is a reason to stop immediately, whatever explanation is offered.
The payment is a push rather than a pull. You instruct your bank to send money, which is the opposite of a card payment where the merchant requests funds. One consequence is that there is no card-style chargeback to fall back on; the dispute route is the operator’s complaints process and the bank’s own error procedures.
What to check inside the bank’s screen
The bank’s confirmation screen is the one piece of the journey that the casino cannot change. Read the payee name, the amount and the reference before approving, and stop if any of the three is not what you expected. A payee name you do not recognise is worth pausing over even if the deposit page looked normal.
Keep the reference the bank generates. That string is how an unmatched incoming payment is found later, and shortening it or replacing it with your own description is the single most common reason a trace fails. Copy it exactly if you record it manually.
Note where you ended up afterwards. A successful journey returns you to the casino and shows the credited balance; an interrupted one can leave you on a loading screen while the payment has already been sent. The loading screen is not evidence of either outcome.
| Stage | Who controls it | What to record |
|---|---|---|
| Bank selection in the cashier | Operator and payment provider | Screenshot of the method and amount |
| Authentication | Your bank | Nothing — never share codes or passwords |
| Payee and amount confirmation | Your bank | Payee name, amount, reference |
| Approval | You | Date and time |
| Return to the casino | Operator | Whether the balance changed |
| Crediting | Operator | Cashier entry and timestamp |
Where the journey breaks
Four failure points recur. The bank selection step cannot reach your bank, which is a provider-side connectivity problem. Authentication fails, which is between you and your bank. The approval completes but the return to the casino does not, leaving the balance unclear. Or the money leaves and the casino does not credit it.
Only the last two are genuinely ambiguous, and they are distinguished by looking in two places rather than one. Check your bank history for a sent payment and check the casino cashier for a credited deposit. The pair of answers tells you which case you are in: nothing sent, sent and credited, sent and not credited, or sent twice.
Do not retry until you have those two answers. A retry when the first instruction already succeeded creates a duplicate payment, and duplicates are far harder to unwind than a single unmatched one, especially where the operator has to handle each reference separately.
- Bank unreachable at the selection step — provider connectivity, retry later.
- Authentication declined — a matter for your bank, not the casino.
- Approved but no return to the site — check bank history before retrying.
- Sent and not credited — collect reference, amount, time, and ask for a trace.
- Sent twice — report both references and ask for one to be returned.
Withdrawals through the same route
A bank-initiated deposit is usually paired with a bank transfer for withdrawals, because the payout leg is a transfer into the same account. In practice that satisfies payment-method matching while being slower than the deposit was, since the outbound rail and the operator’s review are separate things.
Account name matching matters here. The name on the receiving account should match the account holder at the casino; a payout to an account in another name is normally refused, and attempting it can trigger a verification review rather than a payment.
Expect the operator’s processing stage to dominate the elapsed time. The transfer itself may be quick once released, but release follows internal checks, and only the release time is under the rail’s control.
Evidence to keep
Keep four items for each payment: the bank reference, the amount and currency, the date and time of approval, and a screenshot of the cashier immediately afterwards. Those four resolve almost every deposit dispute without any further investigation.
If you need to redact a bank statement before sending it, leave the transaction reference and the payee intact. Redacting the reference is the most common way a customer accidentally makes their own trace impossible.
Never share a banking password, a full set of card details or an authentication code with casino support. A legitimate trace needs a reference, an amount and a time, and nothing that would give anyone access to your account.
Limits, fees and what the bank can block
Two sets of limits apply at once: the operator’s deposit limits and your bank’s payment limits. The lower one wins, and because the bank’s limit can be per payment, per day or per payee, a payment can fail without the casino being involved at all.
Fees on this route are usually absent on the deposit side and possible on the payout side, where a bank transfer may carry a charge. Check both directions rather than assuming a bank-based route is free end to end.
Many banks also offer a gambling block, which stops gambling payments at source. If one is active, the payment will be refused regardless of the method, and that refusal is a consumer control rather than a fault to be worked around.
When to stop and ask instead of retrying
Stop when the bank shows a completed payment and the casino does not show a credit. That is the point at which more attempts make the situation worse and a trace request makes it better. Supply the reference, the amount, the currency and the exact time, and ask whether an unmatched incoming payment exists.
Ask for the answer in writing and keep it. If the payment is found, the matter is closed by a credit. If it is not found, you now have a documented request and a documented reply, which is the beginning of a complaint rather than a conversation.
- Check your bank history for a sent payment before doing anything else.
- Check the cashier for a credited deposit at the same time.
- Do not retry while the outcome is unknown.
- Send reference, amount, currency and timestamp, and ask for a trace.
- Keep the written reply, and escalate through the complaints route if the trace stalls.
FAQ
Does the casino see my banking login?
No. Authentication happens inside your bank’s own journey. Any request for a banking password or authentication code from casino support should be refused.
Is there a chargeback if the deposit goes missing?
Not in the card sense. This is a push payment, so the routes are the operator’s complaints process and your bank’s payment-error procedure, supported by the reference.
Why did my payment fail when my balance was sufficient?
Bank-side limits or a gambling block are the usual causes. Those limits are separate from the operator’s and the lower one applies.
Can I withdraw back to the same route?
Usually as a bank transfer into the account you paid from, which satisfies method matching. The receiving account should be in your own name.
Should I retry if nothing happened?
Only after checking the bank history. If the bank shows a completed payment, retrying creates a duplicate that is harder to resolve than the original problem.
A failed return to the casino page is not the same as a failed bank payment. After approving a transaction in your banking app, check the bank history and the cashier before trying again, and record whether the bank shows no transaction, a pending entry or a completed transfer. The casino loading screen cannot tell you which of those exists.
If the bank shows a transfer and the casino has not credited it, gather the reference, amount, currency and time, and ask the operator to look for an unmatched incoming payment. Do not replace the reference generated by the payment flow with a description of your own; the provider may need the exact string to match it.
Next pages
Sources
- Financial Conduct Authority: information for consumers, checked 18 November 2026.
- UK Gambling Commission: Licence Conditions and Codes of Practice, checked 18 November 2026.
- UK Gambling Commission: age and identity verification, checked 18 November 2026.